OppLoans is almost always cheaper than Integra Credit for the same loan amount. Integra becomes relevant only when OppLoans declines you or does not serve your state.
APR Disclosure
Integra Credit personal loans and lines of credit carry triple-digit APRs (99%–399%) that vary by state and product. These are high-cost credit products designed for borrowers who do not qualify for traditional bank financing. Before applying, confirm you cannot access a lower-cost alternative such as a credit union personal loan, a secured credit card, or employer-based pay advance. Loan amounts, rates, and terms depend on state law and credit review.
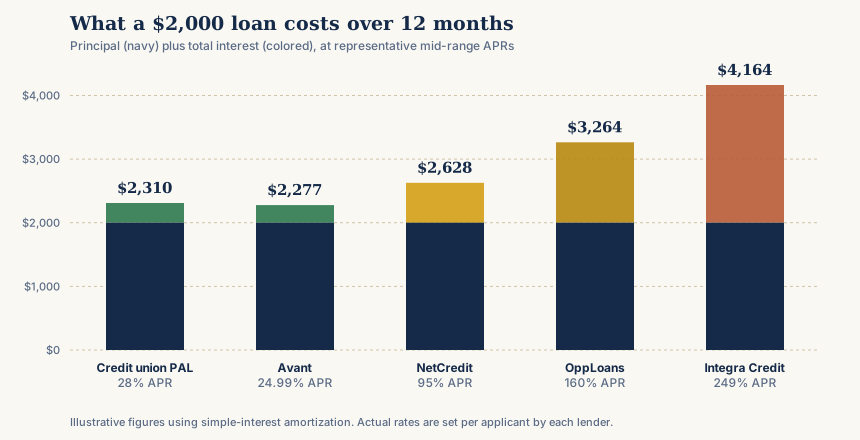
The same $2,000, five different outcomes. At representative mid-range rates, an Integra Credit loan costs about $1,887 more in interest than Avant and about $900 more than OppLoans over twelve months. Illustrative simple-interest amortization; actual rates are set per applicant.
Side-by-side comparison
Integra Credit and OppLoans compared
Feature
Integra Credit
OppLoans
APR range
99%–399%
59%–195%
Loan amount
$500–$3,000
$500–$4,000
Term length
6–24 months
9–18 months
Soft-pull prequalification
Yes
Yes
Origination fee
None
Varies — see detail below
Prepayment penalty
None
None
Funding speed
Next business day
Next business day
Credit reporting
TransUnion
Varies — see detail below
Honest take: OppLoans usually wins on price
OppLoans and Integra Credit serve nearly identical customer segments — subprime borrowers who need small installment loans without a bank or credit union option. Where they diverge is pricing: OppLoans caps its APR around 195%, while Integra reaches 399%. For the same loan amount and term, OppLoans typically costs less.
When OppLoans is the better choice
Your FICO score is 580 or higher
You have at least 60 days of consistent payroll deposits in your bank account
You need a loan amount above $3,000 (OppLoans goes to $4,000)
You live in a state OppLoans serves but Integra does not (and vice versa)
When Integra Credit may still be the right choice
You have been declined by OppLoans
Your FICO is below 550 or you have no credit file
Integra serves your state and OppLoans does not
You specifically want the line of credit product (OppLoans does not offer one)
Credit reporting difference
OppLoans reports to all three major credit bureaus (Equifax, Experian, TransUnion). Integra reports only to TransUnion. If credit building across all three bureaus matters to you, OppLoans has a meaningful advantage.
The practical workflow
If you fit both profiles, check OppLoans first. Prequalification is a soft pull, so there is no cost to trying. If OppLoans declines or offers a rate materially worse than what you expected, then check Integra as a backup. Only accept whichever offer fits your budget.
Abstract APR ranges are hard to weigh. Here is what the difference means on an identical $2,000 loan repaid over twelve months, using a representative mid-range rate for each lender.
Integra Credit and OppLoans compared
Scenario
Integra Credit @ 249%
OppLoans @ 160%
Difference
Loan amount
$2,000
$2,000
—
Term
12 months
12 months
—
Approximate monthly payment
$347
$272
$75/month
Approximate total interest
$2,164
$1,264
$900
Approximate total repaid
$4,164
$3,264
$900
Figures use representative mid-range APRs for illustration. Your actual rate from either lender depends on state, credit profile, and income. Both lenders set rates per applicant.
Ninety days of groceries, roughly, for choosing one application over the other. That is the practical stake in this comparison.
Who each lender actually approves
Both lenders serve subprime borrowers, but the overlap is not total.
Integra Credit's approved profile
Integra publishes no minimum FICO. Reported approvals cluster in the 500–650 range, with verified income weighing heavily in how much is offered. Borrowers with very thin files or recent charge-offs still get approved more often here than at most competitors. Income under $1,500/month typically caps the offer near $1,000.
OppLoans' approved profile
OppLoans also publishes no hard floor but underwrites somewhat more selectively, placing more weight on banking history — account age, overdraft frequency, and income consistency pulled through bank-connection data. A borrower with a very low score but clean, stable banking often does better at OppLoans than the score alone would suggest.
The practical implication: if you were declined by OppLoans, Integra may still approve you. If OppLoans approves you, taking the Integra loan instead costs you money for no benefit.
Loan size and term
OppLoans lends up to $4,000 against Integra's $3,000 ceiling, and offers terms up to 36 months against Integra's 24. Longer terms lower the monthly payment but increase total interest, so the longer-term option is not automatically better — it is better only if the shorter term's payment would push you into missing it.
Fees, beyond the rate
Neither lender charges an origination fee, and neither charges a prepayment penalty. Both are unusual in the subprime tier in that respect, and both deserve credit for it. Late fees exist at both and vary by state.
Because neither charges upfront fees, the APR comparison above is the whole story. There is no scenario where Integra's lower fees offset its higher rate, because the fees are the same: zero.
Credit reporting
This is a meaningful difference that borrowers often miss.
Integra Credit and OppLoans compared
Bureau
Integra Credit
OppLoans
TransUnion
Reports
Reports
Experian
Does not report
Reports
Equifax
Does not report
Reports
If part of your reason for taking the loan is rebuilding credit, OppLoans builds across all three bureaus while Integra builds on one. For a borrower whose goal is qualifying for a car loan or apartment in a year, that difference compounds.
State availability
OppLoans operates in roughly 36 states against Integra's 24. If you are in a state Integra does not serve, this comparison is moot — check our state availability page first.
Where Integra Credit genuinely wins
Being honest about this matters, because a comparison that always picks one side is not a comparison.
Wider credit box at the bottom. Borrowers declined by OppLoans are sometimes approved by Integra.
The line of credit product. OppLoans offers installment loans only. If you need revolving access rather than a lump sum, Integra has a product OppLoans does not.
Smaller minimum in some states. Integra starts at $500 in most states, useful if you need a small amount and do not want to borrow more than necessary.
The decision in one line
Apply to OppLoans first. If approved, take it — the rate is materially lower and the credit reporting is better. If declined, Integra is a legitimate fallback that will likely approve you, at a price you should go in understanding.
Before either, check whether a credit union Payday Alternative Loan is available to you. At a federally capped 28% APR, it beats both by a wide margin. Our alternatives page covers all seven options.
IC
Integra Credit USA Editorial Team
Research & Analysis
Our four-person team researches subprime consumer lending, verifies rate disclosures against state regulator filings, and tracks APR changes across all 24 states where Integra Credit operates. We publish only what we can source — no sponsored rankings, no fabricated reviews, no invented author personas.