Integra Credit Rates and Fees
- 99%–399% APR — the exact range depends on your state, credit profile, and loan term.
- Zero origination fee — you receive the full loan amount, which is rare in this credit tier.
- Zero prepayment penalty — paying early cuts your total interest with no penalty charge.
- Late fees vary by state — typically $15–$30 or 5% of the payment, whichever your state allows.
Our verdict: the fee structure is clean; the interest rate is what makes this expensive.
Exact pricing on Integra Credit installment loans and lines of credit, how the APR is calculated, state variations, and a comparison against mainstream subprime alternatives.
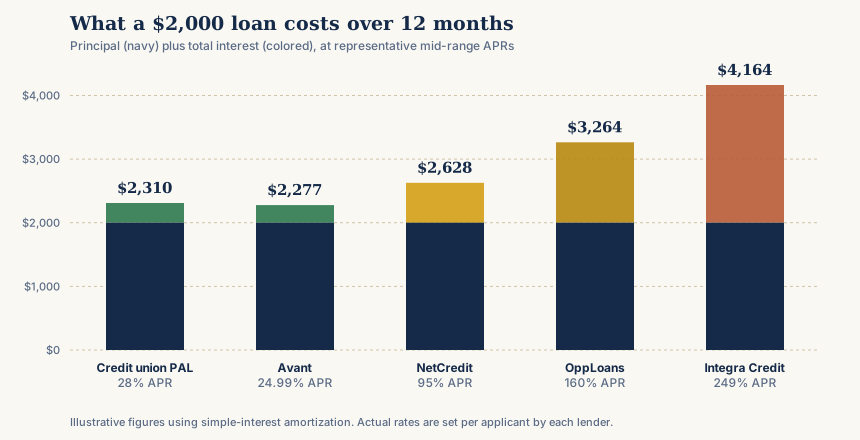
Headline numbers
How Integra sets your APR
Integra does not publish a public rate grid. Your assigned APR depends on three factors:
- State of residence. Each state sets maximum permitted APR for consumer installment loans. California, for example, caps rates lower than Texas or Missouri.
- Loan amount and term. Smaller, shorter loans tend to carry higher APR because fixed origination costs are spread over less principal and time.
- Borrower risk profile. Income, bank account history, and other data from Integra's underwriting model.
You will see your exact APR after prequalification and again in the loan agreement before you sign. Nothing is binding until you accept the final offer.
Sample state APR ranges
| State | Product | Typical APR range | Max loan |
|---|---|---|---|
| Texas | Installment loan | ~149%–399% | $3,000 |
| California | Installment loan | ~99%–299% | $3,000 (min ~$2,600) |
| Ohio | Installment loan | ~149%–249% | $3,000 |
| Missouri | Installment loan | ~149%–399% | $3,000 |
| Kansas | Line of credit | 149%–349% | $3,000 |
| Wisconsin | Installment loan | ~99%–299% | $3,000 |
Ranges reflect published rate and term disclosures as of November 2026 and are subject to change. Your assigned rate will be disclosed in the loan agreement before signing.
Fees beyond interest
- Origination fee: $0. You receive the full approved loan amount.
- Prepayment penalty: $0. Pay off early and only pay interest for the days the balance was outstanding.
- Late fee: Varies by state. Typically $15 to $25 if payment is missed. Check your loan agreement.
- Returned payment fee (NSF): Typically $15 to $25 when a bank draft is returned for insufficient funds.
- Line of credit cash advance fee (where applicable): May apply in some states on certain draw types.
Where Integra Credit fits in the cost hierarchy
| Credit type | Typical APR | When it fits |
|---|---|---|
| Credit union personal loan | 8%–18% | Member in good standing, decent credit |
| Bank personal loan | 8%–25% | Fair to good credit, stable income |
| Online prime lender (Avant, Upstart) | 10%–36% | Fair credit, verifiable income |
| Subprime installment (OppLoans, NetCredit) | 34%–195% | Bad credit, cannot qualify above |
| Integra Credit | 99%–399% | Rejected by subprime lenders above |
| Storefront payday | 300%–600%+ | Avoid in nearly all cases |
Why the APR is this high
Three structural reasons:
- Default rates. Lending to borrowers who have been declined by multiple other lenders carries higher losses. Integra has to price for losses it knows will happen.
- Small-dollar operating cost. The fixed costs of underwriting, servicing, and compliance are the same whether the loan is $500 or $50,000. On small loans, these costs represent a much higher share of each dollar lent.
- Short loan life. With 6- to 24-month terms, the lender has less time to recover its origination investment, so each month must carry more of that cost.
None of this makes Integra affordable. It explains the economics. If you have any cheaper option — and most people do — use it.