Integra Credit Review 2026: Full Lender Breakdown
- We rate it 3.2 out of 5 — legitimate operation, transparent disclosures, but pricing that sits near the top of the legal subprime range.
- Two products — fixed-term installment loans and a revolving line of credit, both $500–$3,000.
- Soft pull first — you can see your rate without a credit-score hit; the hard pull comes only when you accept.
- Next-business-day funding — reliable in most reported cases when verification clears before the daily cutoff.
Our verdict: a real lender doing real lending at a price most borrowers should try hard to avoid.
Integra Credit is a legitimate, BBB-accredited direct lender targeting bad-credit borrowers. It is also one of the most expensive forms of installment credit in the United States. This review covers every operational detail — who owns it, how it is funded, which states it serves, what the loans actually cost, and which competitors beat it on price.
Who operates Integra Credit
The brand is used by several affiliated lending entities under the umbrella of Deinde Financial LLC, a Chicago-based nonbank consumer finance company founded in 2014. The affiliated entities include Deinde Group LLC, Deinde Online Services LLC, Integra Credit One LLC, and Integra Credit Two LLC. Loans are originated either directly by these entities or, in certain states, through bank-partnership arrangements with TAB Bank or CCBank, and serviced by Integra under the brand.
Corporate address: 200 W. Jackson Blvd., Suite 500, Chicago, IL 60606. The company has been BBB-accredited since 2015 and maintains an above-average rating on Trustpilot based on direct customer reviews.
The two products Integra Credit offers
1. Installment loans
Fixed-term, fixed-payment personal loans. You borrow a lump sum between $500 and $3,000 and repay it in equal monthly installments over 6 to 24 months. Terms in most states fall within 9 to 18 months. There is no origination fee and no prepayment penalty — if you repay early, you only pay interest for the days the balance was outstanding.
2. Personal line of credit
Revolving credit with a limit between $500 and $3,000, functioning similarly to a credit card without a physical card. You draw what you need, pay interest only on your outstanding balance, and your available credit is restored as you repay principal. The line of credit product is available in fewer states than the installment loan.
What Integra Credit actually costs
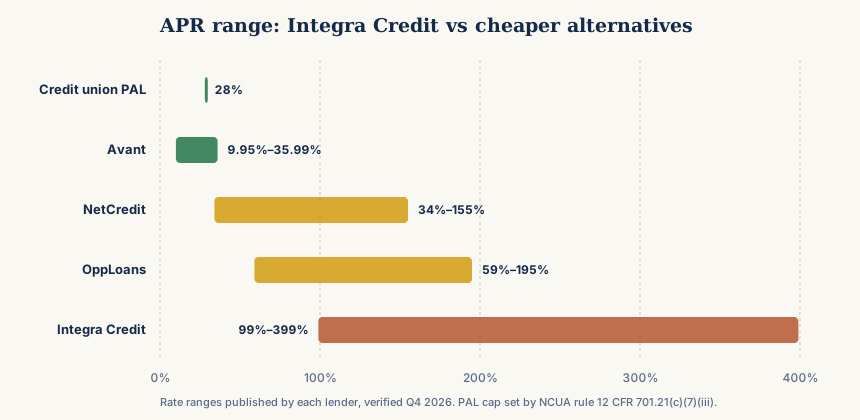
This is where the brutal honesty matters. Integra Credit's advertised APR range is 99% to 399%, with the exact rate depending on your state of residence and loan product. For context:
| Credit tier | Typical APR source | Example rate |
|---|---|---|
| Prime (720+ FICO) | Bank personal loan | 8%–15% |
| Near-prime (660–719) | Upgrade, SoFi | 15%–25% |
| Subprime (580–659) | Avant, Upstart | 25%–36% |
| Deep subprime (<580) | OppLoans, NetCredit | 59%–195% |
| Non-prime/no credit | Integra Credit | 99%–399% |
| Payday-equivalent | Storefront payday | 300%–600%+ |
Integra sits above traditional subprime installment lenders (OppLoans tops out around 195% APR) and below storefront payday lenders. This positioning reflects its market: borrowers rejected by banks, credit unions, and most online installment lenders who still need a structured monthly payment rather than a two-week payday rollover.
For a complete state-by-state APR table, see our rates and fees page.
Honest pros and cons
Pros
- Legitimate, BBB-accredited direct lender since 2015
- Soft-pull prequalification — no credit impact to check your rate
- No origination fee and no prepayment penalty
- Next-business-day funding to your bank account in most cases
- Reports on-time payments to TransUnion — can help build credit history
- Fixed installment structure prevents payday-loan rollover traps
- Line of credit option in select states for recurring short-term needs
Cons
- Triple-digit APR (99%–399%) — dramatically higher than mainstream installment lenders
- Available in only 24 states
- Maximum loan is $3,000 — too small for debt consolidation or major expenses
- Reports to TransUnion only — does not build Equifax or Experian history
- No joint applications or co-signer option
- Limited transparency on minimum credit score and income requirements on public pages
- In some states, loans are issued by bank partners (TAB Bank, CCBank) which can complicate state-rate-cap protections
Who qualifies
The lender does not publish a minimum credit score requirement, but the lender is explicitly positioned for borrowers with bad or limited credit history. Basic eligibility published on the company website:
- Age at least the minimum legal age to contract in your state (typically 18, higher in some states)
- Resident of the United States in one of Integra's serviced states
- Valid US bank account (checking preferred for direct deposit)
- Valid email address and phone number
- Regular source of income
In practice, approval depends on an internal risk model that evaluates income stability, bank account history, employment, and public records. Integra conducts a soft credit pull during prequalification and a hard pull only when you accept a formal offer.
Where Integra Credit lends
The lender operates in 24 states as of November 2026: Alabama, Arizona, Arkansas, California, Delaware, Florida, Idaho, Indiana, Kentucky, Louisiana, Michigan, Minnesota, Mississippi, Missouri, Montana, Nebraska, New Mexico, Ohio, Oregon, Oklahoma, South Dakota, Texas, Utah, and Wisconsin.
Rates and maximum loan amounts vary by state law. California has the highest minimum loan requirement (approximately $2,600) due to state consumer-lending rules. Several states cap maximum APR below Integra's full 399% ceiling.
Is Integra Credit legit?
Yes, the lender is a legitimate company. It is BBB-accredited, maintains a public Trustpilot profile with verified customer reviews, discloses its corporate parent and address, and complies with state consumer-lending licensing where required. It is not a scam.
"Legitimate" and "affordable" are two different questions. Integra is a real lender that will send you real money and report your real payments to the credit bureau. It is also an exceptionally expensive form of credit by any mainstream benchmark. Treat it as a last-resort option after you have ruled out credit union loans, employer pay advances, and secured credit cards.
Cheaper alternatives to consider first
Before applying, check these lower-cost options:
- Local credit union personal loan — Many offer small-dollar loans at 18%–36% APR to members, including those with thin or damaged credit.
- Employer pay advance apps — Earnin, DailyPay, or employer-provided programs can advance earned wages with no or very low fees.
- OppLoans — APR range 59%–195%, available in more states, similar borrower profile.
- NetCredit — Larger loan amounts up to $10,000, APR 34%–155% depending on state.
- Possible Finance — Short-term installment loans, cheaper per-day cost than Integra for small amounts.
See our complete Integra Credit alternatives comparison.
Review methodology
This review is based on publicly disclosed Integra Credit documentation, state-level rate and term filings, cross-referenced coverage from independent personal-finance publications (LendingTree, Bankrate, Benzinga, SuperMoney, WalletHub, MoneyLion), BBB and Trustpilot customer-feedback aggregates, and competitor pricing from direct lender comparison data. We do not accept payment from Integra Credit for editorial coverage. We may earn a commission when readers apply through partner links; this does not influence our ratings. See our full editorial standards and advertising disclosures.
Check your rate without a credit hit
Soft-pull prequalification takes about two minutes and has no impact on your credit score.
Start Prequalification