Integra Credit Alternatives: 7 Options That May Cost You Less
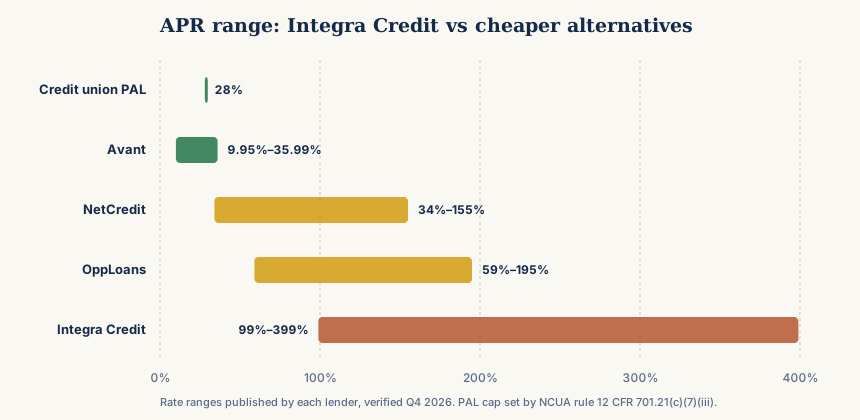
- Credit union PAL caps at 28% APR — by federal rule — roughly one-tenth of Integra’s typical pricing.
- OppLoans runs 59%–195% — serves the same subprime tier at materially lower cost.
- NetCredit runs 34%–155% — larger loans up to $10,000 if your credit supports it.
- Avant caps at 35.99% — requires 580+ FICO but costs a fraction of Integra.
Our verdict: on a $2,000 twelve-month loan, switching from Integra to OppLoans saves roughly $1,400.
Before paying 99%–399% APR, check whether any of these lenders or programs will approve you. For borrowers in the deep subprime tier, several of these consistently beat Integra on price.
Quick comparison table
| Option | APR range | Loan amount | Best for |
|---|---|---|---|
| Integra Credit | 99%–399% | $500–$3,000 | Deep subprime, no file |
| OppLoans | 59%–195% | $500–$4,000 | Subprime with some income |
| NetCredit | 34%–155% | $1,000–$10,000 | Larger loan amounts |
| Avant | 9.95%–35.99% | $2,000–$35,000 | Fair credit or better |
| Possible Finance | ~150%–180% | $50–$500 | Very small short-term needs |
| Credit union PAL | 18%–28% | $200–$2,000 | Credit union members |
| Earnin / Dave / Brigit | Fee or tip-based | $50–$750 | Short-term paycheck gap |
1. OppLoans
OppLoans is the most direct competitor to Integra Credit. Both lenders target subprime borrowers with installment loans, and both offer soft-pull prequalification. The difference is price: OppLoans tops out around 195% APR, while Integra reaches 399%. OppLoans serves a slightly different state footprint and tends to approve applicants with somewhat stronger profiles.
Try OppLoans first if: Your FICO is 580+ and you have stable employment income deposited to your bank account.
2. NetCredit
NetCredit is owned by Enova International, the same parent company that operates CashNetUSA and several other subprime brands. APRs range from 34% up to 155% depending on state and borrower, with loans up to $10,000 — well beyond Integra's $3,000 cap. Use NetCredit if you need a larger loan amount or if your profile is closer to subprime than deep subprime.
Try NetCredit first if: You need more than $3,000 or your credit is in the 580–659 range.
3. Avant
Avant serves fair-credit borrowers with APRs starting around 10% and capping at 35.99%. Minimum loan amounts start at $2,000, so this is not an option for sub-$2,000 needs. Avant performs a soft-pull prequalification just like Integra.
Try Avant first if: Your FICO is 580+ and you need $2,000 or more. The savings versus Integra on the same loan amount are substantial.
4. Possible Finance
Possible Finance offers very small installment loans ($50–$500) repaid over four scheduled payments. The APR is in the same triple-digit range as Integra, but because the loan amount and duration are smaller, the absolute dollar cost per loan is lower. Possible also reports to credit bureaus and can be a credit-building tool.
Try Possible first if: You need $500 or less for a short-term gap.
5. Credit union Payday Alternative Loans (PALs)
Federal credit unions are permitted to offer PAL loans at APRs capped at 28%, in amounts from $200 to $2,000. You must typically be a credit union member for at least one month to qualify. If you are not currently a credit union member, this is the single highest-impact action you can take for future low-cost borrowing — join a local credit union today.
Try credit union PAL if: You are an existing credit union member or willing to join one.
6. Earned wage access and cash advance apps
Apps like Earnin, Dave, Brigit, MoneyLion, Chime SpotMe, and Albert advance earned wages or offer cash advances based on your bank account activity, not your credit score. Costs come as subscription fees, instant-funding fees, or optional tips — typically much cheaper than any installment loan APR when you need only $50 to $500 for a few days.
Try cash advance apps if: You need $50–$500 and will be paid within 1–2 weeks.
7. Employer earned wage access programs
Many employers now offer earned wage access programs (DailyPay, Payactiv, Rain) that let you receive wages you have already earned ahead of payday. These are typically the cheapest option when available — often with no cost at all or a small flat per-transfer fee.
Try employer EWA if: Your employer offers such a program and you have earned wages pending.
What to do if nothing cheaper will approve you
If you have tried credit union PALs, OppLoans, NetCredit, and Avant and been declined, and you have a genuine short-term need you cannot meet otherwise, Integra Credit is a legitimate option. In that case:
- Borrow only what you truly need — do not round up
- Choose the shortest term that keeps the monthly payment affordable
- Plan to pay off early if your situation improves — no prepayment penalty
- Set up automatic payments to avoid late fees
- Treat it as a one-time emergency tool, not a recurring source of credit